How to Build a Diversified Investment Portfolio
A practical guide to modern portfolio construction: asset allocation models, geographic diversification, risk profiles, and rebalancing protocols.
Oct 30, 2026 • 9 min read

Demystify the capital markets with this beginner roadmap covering asset classes, index funds, risk management, and the power of compound interest.
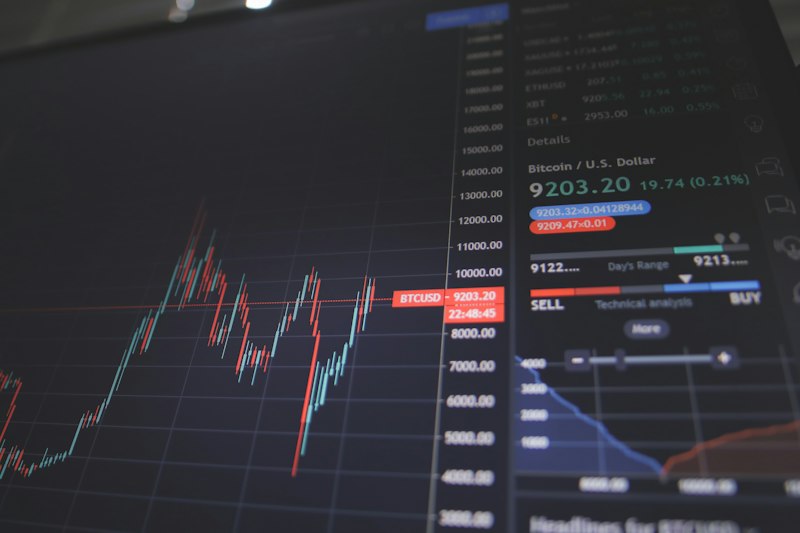
Many individuals view investing as an intimidating hybrid of high finance, Wall Street jargon, and reckless gambling. Images of traders shouting across trading floors or volatile cryptocurrency charts lead people to believe that investing is reserved for financial elites.
In reality, modern investing is straightforward, accessible, and essential. You do not need an economics degree, nor do you need thousands of dollars to begin. With low-cost fractional shares and broad-market index funds, anyone with $20 or ₹500 can become an owner of the world’s most profitable corporations.
All equity and debt investments carry risk of capital loss. Past market returns do not guarantee future performance. Ensure an emergency fund is in place before committing capital to market instruments.
To understand why investing is necessary, consider the silent destroyer of wealth: inflation.
If consumer prices rise by an average of 5% annually, a $100 basket of groceries will cost $163 a decade from now. If your money remains idle in a standard checking account earning 0.5% interest, you are losing real wealth every single day.
Investing allows you to harness the power of compound interest, described by Albert Einstein as the eighth wonder of the world:
Formula:
A = P (1 + (r / n))^{nt}
Where your initial principal ($P$) earns returns ($r$), and those returns subsequently generate their own returns over time ($t$).
| Initial Investment | Monthly Contribution | Assumed Annual Return | Net Value After 10 Years | Net Value After 25 Years | Net Value After 40 Years |
|---|---|---|---|---|---|
| $1,000 | $250 | 8% Annualized | $47,560 | $223,780 | $878,570 |
| $1,000 | $500 | 8% Annualized | $94,120 | $446,560 | $1,756,140 |
| $1,000 | $1,000 | 8% Annualized | $187,240 | $892,120 | $3,511,280 |
Notice that between year 25 and year 40, your wealth quadruples. The vast majority of compounding gains arrive at the tail end of your investing horizon.
Diversifying capital requires understanding the fundamental building blocks of investing.
Buying a share of stock makes you a fractional owner of an operating business (such as Apple, Microsoft, Reliance, or HDFC). If the business expands its revenues and profits, the value of your shares appreciates, and you may receive direct cash distributions via quarterly dividends. Equities provide the highest historical long-term returns, balanced by short-term price volatility.
When you purchase a bond, you lend money to a sovereign government or corporation in exchange for guaranteed periodic interest payments and full return of principal upon maturity. Bonds offer lower returns than stocks but provide stability and ballast during market panics.
Physical residential or commercial property generates rental income and potential capital appreciation. Modern investors can also access liquid real estate through REITs (Real Estate Investment Trusts), which trade on stock exchanges like standard equities.
Ultra-short-term debt instruments that preserve capital and provide liquidity, suitable for emergency reserves and short-term financial targets.
For 95% of retail investors, passive index funds (such as those tracking the S&P 500, Total World Stock Index, or Nifty 50) represent the most reliable path to wealth. They eliminate individual stock-picking risk, reduce expense ratios to near zero, and consistently outpace active fund managers.
| Optimal Investment Vehicle | Broad-Market Index ETFs / Direct Index Funds |
| Recommended Holding Period | Minimum 5 to 7 Years |
| Target Expense Ratio | Below 0.20% per annum |
Modern brokerage platforms have eliminated trading commissions and introduced fractional share investing. You can begin investing in low-cost index funds with as little as $10 or ₹500.
Pay off all high-interest consumer debt (credit cards, personal loans carrying over 10% APR) first. However, low-interest debt like manageable mortgages or student loans should not stop you from capturing an employer retirement match or building long-term equity exposure.
With fractional share trading and low-minimum systematic investment plans (SIPs), beginners can initiate their investment journey with small incremental amounts. Consistency and time in the market matter vastly more than starting capital size.
The biggest mistake is loss aversion and panic selling during inevitable market corrections, combined with FOMO (fear of missing out) buying at market tops. Successful investing requires emotional detachment and adhering to a pre-defined asset allocation framework.
Dollar-cost averaging or systematic monthly investing eliminates the stress of market timing by purchasing more units when prices dip and fewer when prices rise. For regular salary earners, systematic monthly allocation matches cash flow dynamics perfectly.
A practical guide to modern portfolio construction: asset allocation models, geographic diversification, risk profiles, and rebalancing protocols.
Master the art of patient wealth accumulation: buy-and-hold philosophy, dollar-cost averaging, asset rebalancing, and overcoming cognitive behavioral traps.